About Mote Financial
Independent Medicare guidance — multi-carrier, carrier-paid, and a real person on the call.
Mote Financial is an independent agency helping clients across Florida, Georgia, and South Carolina navigate Medicare with clarity and confidence. We compare Medigap, Medicare Advantage, Part D, dental / vision / hearing, and final-expense plans across the carriers we are appointed with — so the recommendation fits your doctors, your prescriptions, and your budget, not a single plan sheet.
Or send a note: mote-financial@polsia.app — or call 229-469-1201.
What you'll find on this page
- · Our story — why we started, how we work, and who you will be talking to
- · Carriers we work with — the appointed product families (no brand names)
- · Why an independent advisor — vs. captive agents and direct carriers (1-800-MEDICARE, carrier call centers)
- · A personal next step at the bottom
Skim or read end-to-end — the page is short and the sections are self-contained.
Our story
Independent by structure, year-round by practice.
Mote Financial was founded to do one thing well — give every client the same careful, year-round Medicare guidance an insider would give their own family. The short version is below; the longer conversation is the consultation.
Our story
Why we started Mote Financial
Medicare is a system most people only encounter once, and the cost of getting it wrong is felt for years. Mote Financial was founded to do one thing well — give every client the same careful, year-round guidance an insider would give their own family. No quotas, no single-carrier pressure, no commissions on the front end of the conversation.
Our story
Independent by structure, not by slogan
We are appointed across multiple carriers so the recommendation is built around the client, not the carrier we happen to be captive to. The same plan letter from two different carriers covers the same things — we compare on price, network, rate-history, and how the plan treats your specific prescription list. Independence is the structural reason the advice fits.
Our story
The conversation does not end at enrollment
AEP reviews, claims help, birthday check-ins, billing questions — answered by the same person who enrolled you. Most of our clients came in during their first year on Medicare and stayed on through every Annual Election Period since, because the relationship is the point.
Meet Donald Mote
Donald Mote — founder, licensed advisor, and the person on the call.
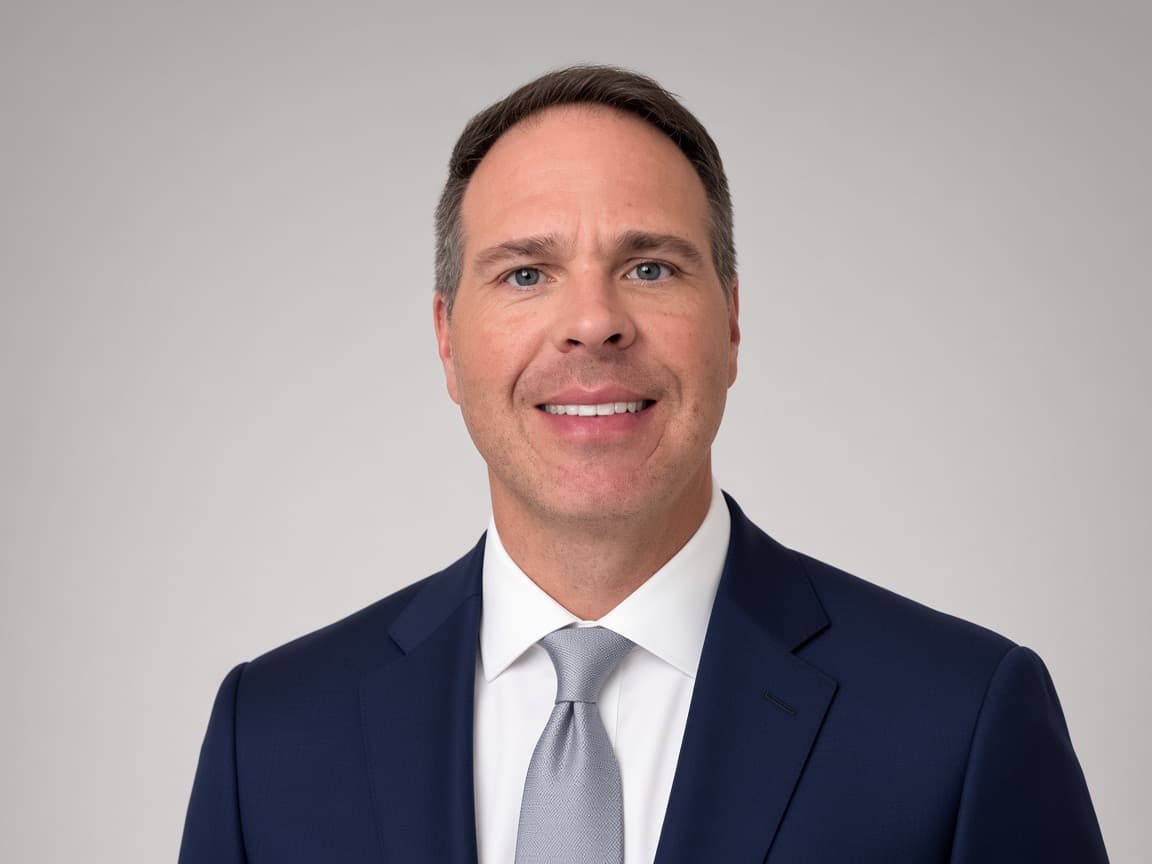
Hi, I’m Donald Mote, and for the past 10 years I’ve had the privilege of helping people make sense of Medicare and life insurance. But I’ve actually been in the “helping people” business for more than 20 years.
I believe insurance doesn’t have to be confusing, complicated, or filled with industry jargon. My job is to listen, answer your questions, and help you find coverage that makes sense for you — not just sell you a plan.
When I’m not in the office helping clients, you’ll probably find me on the golf course or in the kitchen cooking for my family. At the end of the day, I enjoy helping people, solving problems, and knowing I’ve made someone’s decision a little easier.
Have questions about your insurance options? Let’s talk. Fill out the contact form and I’ll get back to you shortly. No pressure, no confusing sales pitch — just straightforward help from a real person.
Carriers we work with
Appointed across the five product families that matter.
Mote Financial is an independent agency — not captive to a single carrier. We are appointed across the product families below so the recommendation fits your situation, not a single plan sheet. We name the families here and the carriers by appointment on the call.
- · Multi-carrier by appointment, not by slogan
- · Carrier-paid only after you enroll
- · Licensed in Florida, Georgia, and South Carolina
01 · Product family
Medicare Supplement (Medigap)
Standardized Plan A through Plan N, side by side.
We compare every standardized Medigap plan (A–N) across the carriers we are appointed with, paired with the standalone Part D plan that fits your drug list and your local pharmacy. Same coverage letter, different price and rate-history — the recommendation is built on that.
02 · Product family
Medicare Advantage (Part C)
HMO / PPO bundles, walked through line by line.
Network, drug formulary, dental and vision add-ons, prior-authorization rules, and the yearly out-of-pocket maximum — every line on the page explained in plain language so an attractive premium does not hide the cost picture.
03 · Product family
Standalone Part D
Prescription drug coverage that matches your list.
Annual review of your medications against the formulary and preferred-pharmacy network of every available Part D plan — small savings most people miss each year, and large savings when an expensive brand-name moves tiers.
04 · Product family
Dental · Vision · Hearing
Add-ons that round out the coverage.
Standalone dental, vision, and hearing plans paired with a Medigap or Medicare Advantage setup — routine cleanings, frames and lenses, hearing-aid fittings, and the bigger procedures Original Medicare does not cover.
05 · Product family
Final-expense coverage
Small whole-life policies that protect the family.
Modest face-amount whole-life plans designed to cover funeral costs, final medical bills, and the immediate expenses that fall on a spouse or adult child — underwritten simply, with no medical-exam requirement for many applicants.
Why an independent advisor
Who answers the phone shapes the recommendation.
Every Medicare decision eventually runs through one of three paths — an independent advisor, a captive agent, or a direct-carrier call (1-800-MEDICARE and the carriers’ own call centers). Each path has a use. The comparison below is the honest one, not the marketing one.
Multi-carrier
Independent advisor
Appointed with multiple carriers. The recommendation is built around the client.
- · Compares plans across every carrier the advisor is appointed with — not just one plan sheet
- · Walks through Medigap, Advantage, and Part D side by side on the same call
- · Compensation is carrier-paid, disclosed up front, and identical regardless of which carrier you choose
- · Year-round service: AEP reviews, claims help, billing questions — the same person on the phone next year
- · Independent by structure, not by slogan — the appointment letters are the proof
Single-carrier
Captive agent
Works for one carrier. The recommendation starts from one plan sheet.
- · Licensed and trained to sell one carrier’s products — sometimes more than one, but always within a defined set
- · Deep on that carrier’s plans; not set up to compare alternatives across the market
- · Annual reviews typically focus on that carrier’s newest plan year, not the broader market
- · Service is solid for that carrier’s plans; outside that universe the conversation ends quickly
No-carrier
Direct carrier (1-800-MEDICARE & carrier call centers)
You call the carrier, or 1-800-MEDICARE, and work with whichever agent picks up.
- · 1-800-MEDICARE is the official federal line — accurate on rules and enrollment windows; not set up to recommend a specific plan
- · Carrier call centers sell only that carrier’s plans; comparison across carriers is on you
- · You may reach a different agent on every call — no relationship, no annual review reminder
- · Useful for factual questions and enrollment; less useful when the decision is "which of these fits me best"
Ready to talk?
A 30-minute, no-cost conversation is the cleanest next step.
Bring your doctors, your prescription list, and the question that sent you here. We will walk through it on a phone or video call, no slides, no sales pressure, and you leave with a side-by-side comparison you can act on — or not — at your own pace.
- · No cost. No obligation. Carrier-paid only after you enroll.
- · Independent — multi-carrier comparison, not a single plan sheet.
- · A real person on the call — and the same person on the phone next year.